MicroStrategyStrategymNAVBTC YieldPreferredsCase study

MicroStrategy's balance-sheet strategy: Strategy's financial engineering explained

·10 min read·
🇪🇸 Leer este artículo en español →
Gold bitcoins representing MicroStrategy's Bitcoin balance sheet.
Key points
  • 01Strategy's model is not 'buy and hold': it is raising capital in public markets (convertible debt, ATM offerings, preferreds) and deploying it into Bitcoin continuously.
  • 02The key is issuing capital when the stock trades at a premium to its Bitcoin value (mNAV > 1): each issuance buys more BTC than it dilutes, raising Bitcoin per share (BTC Yield).
  • 03The engine works while there is a premium and access to cheap capital; when mNAV compresses, the machine slows. Knowing that limit is understanding the model.

Build your Bitcoin investment portfolio

Create your free portfolio and track your Bitcoin exposure —treasuries, ETFs and direct BTC— in one place, with weighted mNAV and BTC Yield.

Create my portfolio →

Strategy (formerly MicroStrategy) is the largest Bitcoin treasury in the world, with 848,517 BTC on its balance sheet. But reducing its story to "they bought a lot of Bitcoin" misses the point. What Michael Saylor built from August 2020 is a financial-engineering machine that converts access to capital markets into Bitcoin per share. This is the case study every company considering the treasury model should understand.

The starting point: August 2020

MicroStrategy was a business-intelligence software firm with substantial cash being eroded by inflation. In August 2020 it converted $250 million of that cash into Bitcoin, the largest corporate purchase of its kind at the time. Three months later it surpassed $450 million. So far, this is a treasury decision. What came next created the category.

The engine: raising capital to buy more Bitcoin

Instead of limiting itself to its cash, Strategy began raising capital in public markets to buy more Bitcoin. It used three main tools, worth understanding:

Convertible debt. Bonds that pay low interest and that the investor can convert into shares if the stock rises. Strategy issued billions at very low rates — in some tranches, at 0% — because the investor paid for that discount in exchange for the conversion option.

ATM (at-the-market) equity offerings. Issuing new shares directly into the market, at the current price, continuously.

Perpetual preferred shares. Since 2025, Strategy issues preferreds — STRK at 8%, STRF at 10%, STRC at 12% with two payments a month, STRD — that raise capital from institutional fixed-income investors in exchange for a fixed dividend, without directly diluting the common stock.

Every dollar raised through these channels was deployed into Bitcoin.

The key: issuing at a premium to NAV

Here is the genius and the point to grasp. Strategy's stock usually trades at a premium to the value of its Bitcoin on the balance sheet: that is mNAV, the multiple of market cap over the net value of the BTC. When mNAV is above 1, issuing new shares at that price lets the company buy more Bitcoin than the dilution costs existing shareholders. The result is that Bitcoin per share grows — the metric Strategy calls BTC Yield — without the shareholder putting in another cent. The market pays a premium for that value-creation machine, and that premium feeds the machine.

Why it works… and where the limit is

The engine is reflexive: high premium → ability to issue cheap capital → more Bitcoin per share → more confidence → high premium. But it works both ways. When mNAV compresses toward 1 (or below), issuing shares stops creating value and can destroy it, the cost of capital rises, and the ability to keep accumulating slows. That is why following mNAV is following the health of the model. Strategy traded at premiums above 3x in moments of euphoria; understanding that the premium is neither free nor permanent is understanding the model's risk. Our stress test shows the BTC price at which the structure runs out of margin.

What a company can learn

The replicable lesson is not "issue convertible debt." It is deeper: a treasury's value lies not only in how much Bitcoin it holds, but in its ability to grow Bitcoin per share over time using capital-market tools with discipline. Not every company has access to those markets or the scale to do it efficiently, and that is where most would be better off getting exposure through a vehicle that already masters this engineering — such as Standard 21, of whose ecosystem SatsIntel is the data arm — rather than trying to replicate it from scratch.

Summary

MicroStrategy/Strategy's balance-sheet strategy is the founding manual of corporate Bitcoin: raise capital at a premium, convert it into Bitcoin, grow BTC per share, repeat. It is brilliant while there is a premium and access to capital, and fragile when both disappear. You can follow its mNAV, BTC Yield and holdings live on its SatsIntel profile.

This article is education and analysis, not investment advice. Investing carries the risk of loss.

Frequently asked questions

What is MicroStrategy's Bitcoin strategy?

MicroStrategy (Strategy) converts access to capital markets into Bitcoin. It raises capital through convertible debt, share offerings (ATM) and preferred shares, and deploys that capital into buying Bitcoin continuously, aiming to grow Bitcoin per share over time. It is not 'buy and hold' — it is a leveraged accumulation machine running on public markets.

What is Strategy's mNAV and why does it matter?

mNAV is the multiple of the company's market cap over the net value of its Bitcoin. When it is above 1 (a premium), Strategy can issue shares at that price and buy more Bitcoin than it dilutes, raising Bitcoin per share. When mNAV compresses toward 1, issuing stops creating value and the machine slows. That is why mNAV is the model's thermometer.

How does Strategy finance Bitcoin purchases without diluting so much?

It combines convertible debt (at very low rates thanks to the conversion option), ATM equity offerings when trading at a premium, and perpetual preferred shares (STRK, STRF, STRC, STRD) that raise fixed-income capital in exchange for a fixed dividend without directly diluting common stock. The key is issuing at a premium to the value of its Bitcoin.

What is the risk of the MicroStrategy model?

The model is reflexive: it depends on maintaining a premium (mNAV > 1) and access to cheap capital. If the premium compresses or the market closes, issuing capital stops creating value per share and the ability to keep accumulating shrinks. Bitcoin's volatility amplifies the stock's moves in both directions.

Found this useful? Share it:
Stacked Bitcoin coins, illustrating Strategy's (MicroStrategy's) corporate Bitcoin reserve.
StrategyMicroStrategy

How many bitcoin does MicroStrategy hold? 848,517 BTC (Oct 2026)

→ Strategy holds 848,517 BTC (October 28, 2026): the world's largest corporate Bitcoin treasury, ~4% of total supply and close to 66% of all the BTC held by listed companies.

Jun 25, 20268 min
Conceptual scale weighing a treasury company's dollar obligations against the Bitcoin on its balance sheet
StrategyTreasuries

Can a Bitcoin treasury company be forced to sell? Strategy's 2026 pivot

→ A Bitcoin treasury company with no secured debt cannot receive a margin call on its BTC: the real risk isn't collateral, it's the dollar cash needed to pay preferred dividends and interest.

Jul 28, 202614 min
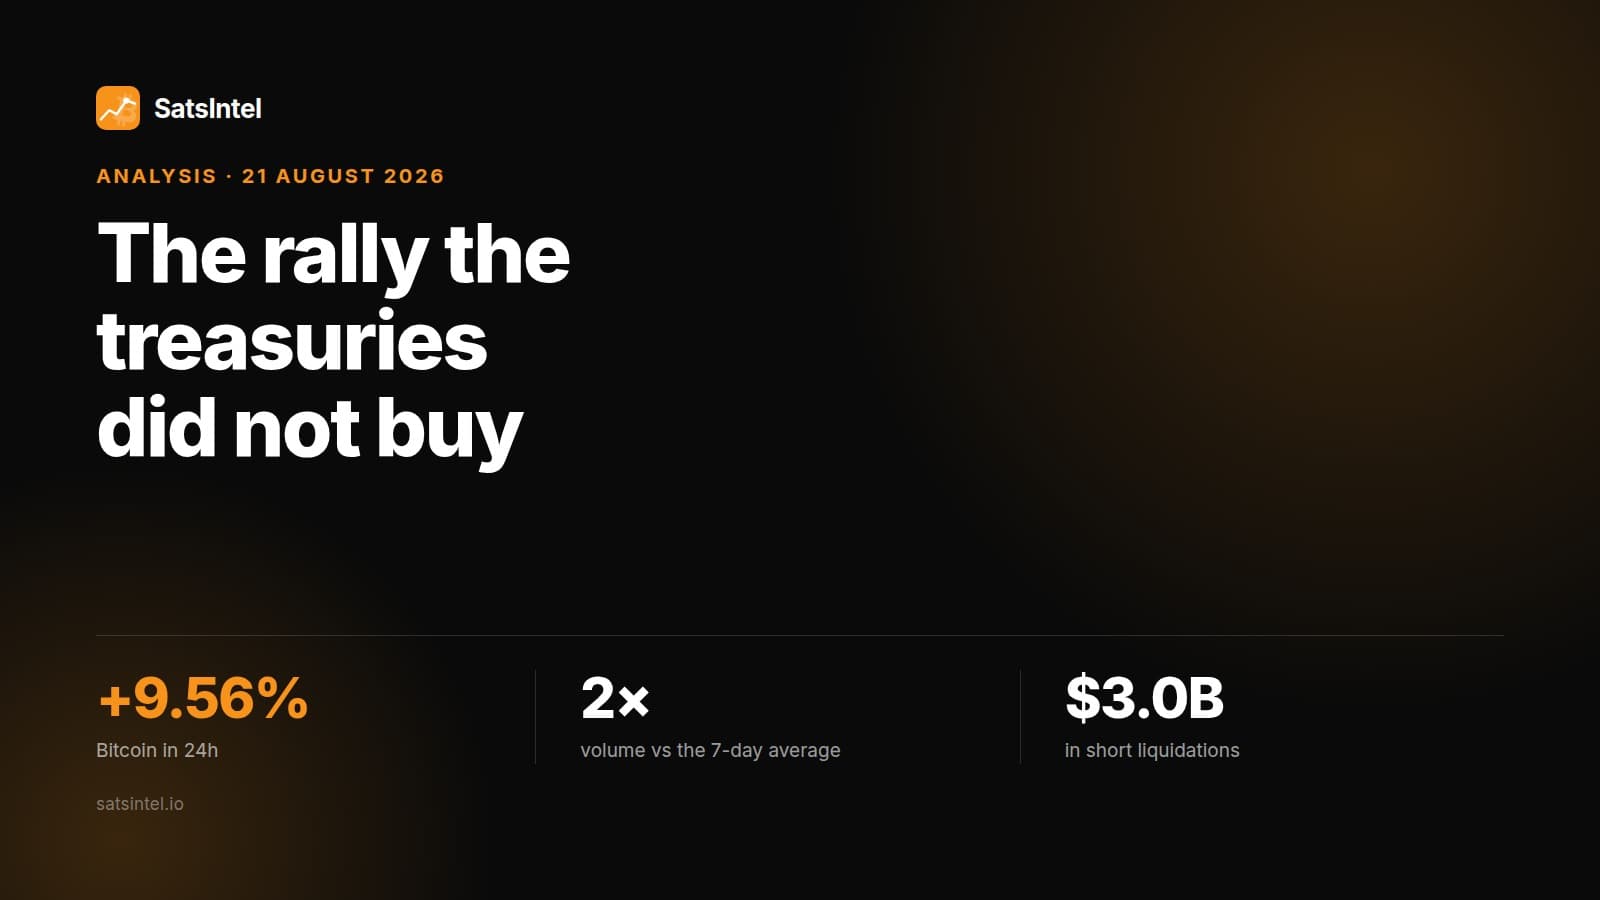
Cover of the post on the Bitcoin rally of 21 August 2026, with the three key figures: a 9.56% 24-hour gain, double the trading volume and $3 billion in short liquidations
AnalysisTreasuries

The rally the treasuries did not buy

→ $63.7 billion in 24-hour volume, 101.9% above the average of the previous seven days.

Aug 21, 20268 min
Financial analysis charts illustrating Strategy's balance sheet strategy and its Bitcoin sales
StrategyPreferreds

Why Strategy is selling Bitcoin: the three sales of 2026 and what is driving them

→ Strategy has sold 5,258 BTC in 2026 across three transactions —32, 3,588 and 1,638 BTC— and still holds 848,517: what it has sold is 0.6% of the position.

Aug 5, 20269 min
Candlestick chart of a financial market on a screen
STRCSATA

STRC vs SATA: which Bitcoin preferred pays more — and which held up better? (August 2026)

→ SATA pays 13% a year in ~250 daily installments (compounded effective yield ~13.9%) and trades near par; STRC pays 12% semi-monthly and closed July at $89.46, 10% below its $100 par.

Jul 15, 202612 min
Banknotes and coins stacked on a work desk
PreferredsDigital Credit

Bitcoin preferred stocks: what they are, how they work and who issues them (2026 guide)

→ A Bitcoin preferred is a perpetual security paying a fixed or variable dividend on a par value (typically $100), issued by a company whose solvency rests on its Bitcoin treasury and its access to capital markets.

Jul 14, 202610 min
Physical Bitcoin coin on a computer motherboard with illuminated circuits
STRCDigital Credit

STRC and the rise of Digital Credit: Strategy's monthly preferred comes to the blockchain

→ STRC raised $2,521M in its July 2025 IPO: the largest perpetual preferred offering in the US since 2009 and the largest US IPO of the year.

May 7, 202612 min
Financial chart illustrating the premium over a Bitcoin treasury's NAV.
mNAVValuation

The mNAV thesis: when it's worth paying a premium over a company's Bitcoin value

→ An mNAV of 2x means the market values the company at twice the value of its Bitcoin.

Feb 17, 20267 min

Did you find this analysis useful?

Get a weekly editorial digest of what matters most in corporate Bitcoin. The issues are written in Spanish.